
Daily Podcast full article
Semicon West toasts $1 trillion
At SEMICON West 2026, the semiconductor industry marked its first $1 trillion annual revenue milestone with a champagne toast, while fresh China trade data showed how the same AI cycle is pushing chip export values sharply higher: China’s integrated-circuit exports jumped 136% year on year in September to roughly $45 billion [1][3].
A toast, but not a victory lap
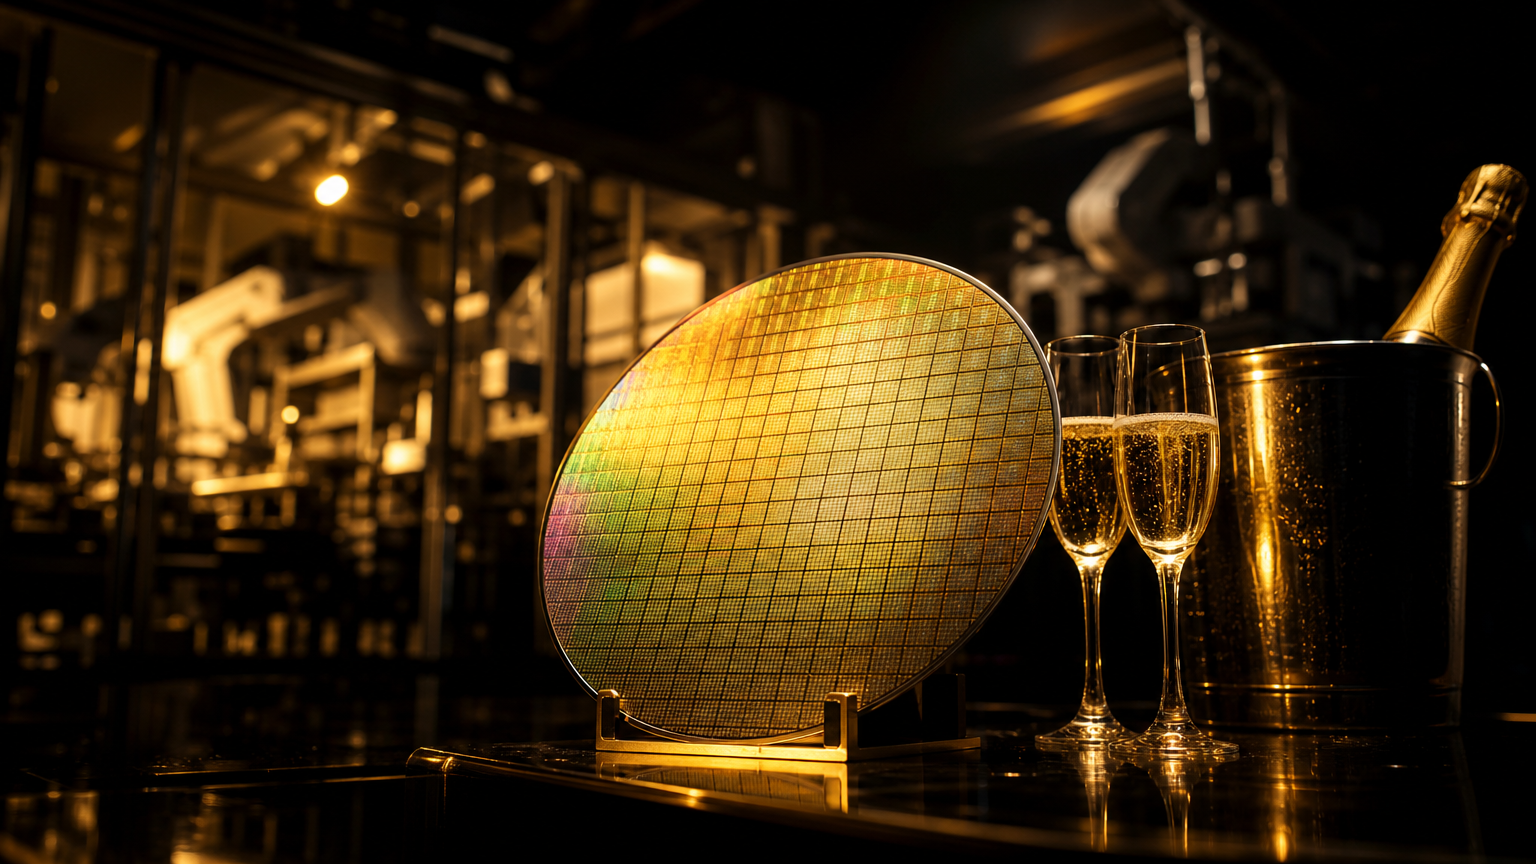
SEMICON West opened in San Francisco with a deliberately theatrical signal: a bottle of champagne for an industry that has crossed $1 trillion in annual revenue for the first time . The toast mattered because it turned a technical supply-chain story into a macroeconomic one. Chips are no longer merely components inside phones, servers, cars and factory equipment. At trillion-dollar scale, they are infrastructure, industrial policy, capital expenditure, energy demand and geopolitical leverage compressed onto silicon.
The timing also made the celebration more pointed. The milestone arrived nearly four years ahead of earlier projections, according to reporting from the event, and the opening program framed the moment around AI, advanced manufacturing, packaging, supply-chain resilience and the next phase of semiconductor capacity . In other words, SEMICON West was not simply congratulating the industry for selling more chips. It was marking the moment when chips became one of the world’s defining economic systems.
That is why the champagne image works. Moore’s law may have supplied the long-term mythology, but the immediate accelerant is the AI build-out: GPUs, high-bandwidth memory, advanced packaging, power delivery, inspection, metrology, substrate capacity and the wafer-fab equipment that turns demand forecasts into physical plants. The industry can celebrate the revenue line, but every glass raised at Moscone Center also pointed to a harder question: who can build enough capacity, fast enough, without breaking budgets, grids or supply chains?
The $1 trillion milestone is turning into a capex race
The strongest evidence that the milestone is more than symbolic came from SEMI’s new equipment-spending outlook released at SEMICON West. SEMI projected global 300mm front-end fab equipment spending at $149 billion in 2026, up 31% year on year, with investment expected to keep growing at double-digit rates through 2029 and reach $227 billion . That is the industrial version of the champagne toast: if revenue has crossed $1 trillion, factories and tools now have to catch up.
The same forecast showed how broad the build-out has become. Excluding pure R&D fabs, SEMI projected 20 new 300mm fabs or production lines beginning construction worldwide in 2026 and another 18 in 2027 . The United States is part of that wave, with three such starts projected in 2026 and four in 2027 . Fab construction spending is also expected to rise sharply, from $47.5 billion in 2026 to $63.3 billion in 2027 and $68.4 billion in 2028 .
Those figures clarify what “$1 trillion” means in practice. It means more lithography, etch, deposition, cleanroom, inspection and automation demand. It means longer negotiations over tools, materials and skilled labor. It means public subsidies and national strategies will continue to collide with corporate capital discipline. It also means that the industry’s bottlenecks are no longer limited to leading-edge logic. Memory, packaging, power, thermal management and mature-node capacity all become strategic when AI infrastructure is scaling at this speed.
The event’s tone reflected that shift. TechTimes reported that SEMICON West’s sold-out floor brought together more than 35,000 attendees and 734 exhibiting companies across 1,500 booths . That is not just a trade-show statistic. It is a sign that the semiconductor supply chain has become a crowded field of strategic participants: toolmakers, foundries, design firms, materials suppliers, policymakers, investors and customers all trying to position themselves for the post-$1 trillion cycle.
China’s export surge shows the demand shock is global
The second half of the story came from China’s trade data. South China Morning Post reported that China’s integrated-circuit exports surged 136% year on year in September to US$45 billion, outpacing the 108% growth rate recorded for the first nine months of the year . The value jump was especially striking because September export volume rose only 1% year on year to 32.7 billion IC units . The implication is clear: prices, mix and demand intensity—not just unit growth—are doing much of the work.
Shanghai Metals Market, citing China’s General Administration of Customs, put September IC exports at US$44.951 billion, up 136% year on year . The customs-linked figure helps anchor the scale of the move: this was not a vague “AI optimism” headline, but a measurable trade surge in one of the most important semiconductor categories.
For the first three quarters, China exported 275.2 billion IC units worth nearly US$302 billion, according to the same customs-based reporting cited by SCMP . That gives the export surge a structural dimension. China is not merely benefiting from one hot month. It is capturing value from a broader repricing of semiconductor supply as AI infrastructure pulls memory, processors and supporting silicon into a tighter market.
The contrast between value and volume is the key analytical point. A 1% rise in units alongside a 136% rise in value suggests that average export values have risen dramatically, likely reflecting a combination of higher memory pricing, product mix changes and demand for more valuable components. It also shows why export controls have not produced a simple decline in China-linked semiconductor trade. Restrictions may limit access to the most advanced tools and AI chips, but they can also reshape the product mix, redirect procurement and raise the value of available supply.
Controls, shortages and the new geography of value
The China export data landed in the middle of continuing technology controls and supply-chain realignment. That makes the numbers politically sensitive. If Chinese IC exports are rising this sharply despite restrictions, then the global chip economy is not fragmenting in a clean or linear way. Instead, it is rerouting.
For buyers, the message is pragmatic. When AI demand pushes up prices and tightens supply, procurement teams search across every available source. Chinese suppliers may not dominate the most advanced accelerator segment, but they can gain from shortages in memory, mature-node ICs, supporting components and electronics supply chains. The result is a market in which export value can surge even when the geopolitical environment remains hostile.
For policymakers, the message is more uncomfortable. A trillion-dollar semiconductor industry attracts subsidies, export controls, investment screening and strategic stockpiling. Yet the same demand wave that justifies those interventions can reduce their neatness. Controls aimed at suppressing certain capabilities may not suppress total trade value; they may instead push value into different nodes, categories and geographies.
That is why the SEMICON West toast and China’s export spike belong in the same story. One marks the industry’s arrival as a trillion-dollar platform. The other shows how quickly that platform redistributes revenue when AI creates scarcity. The celebration in San Francisco and the customs figures from China are two views of the same cycle: chips have become the hard infrastructure of the digital economy, and the world is paying more to secure them.
After the champagne, the pressure begins
The most important word after “trillion” is not “celebration.” It is “capacity.” SEMI’s projection that 300mm equipment spending could reach $227 billion in 2029 shows that the industry is preparing for a larger, more capital-intensive era . China’s September export surge shows that the revenue effects are already visible in trade flows . AP’s broader trade reporting adds that China’s total exports rose 36.3% in September and that its January-to-September trade surplus reached $938 billion, increasing pressure from trading partners to rebalance trade .
That wider trade context matters because semiconductors now sit at the intersection of AI demand, industrial policy and external balances. If chip values rise faster than volumes, countries with manufacturing scale can record large export gains even without proportional increases in physical shipments. If AI data-center demand remains strong, memory and component pricing can continue to amplify those gains. If new fab capacity arrives later than expected, the pricing pressure could last longer than buyers want.
So the SEMICON West toast was justified, but it was not the end of the story. It was the opening ceremony for a more expensive phase of the semiconductor cycle. The industry has crossed $1 trillion. Now it must prove that it can build the factories, train the workforce, secure the materials, power the data centers and manage the politics that come with that scale.
Moore’s law may have finally unlocked the champagne. The next test is whether the industry can keep the bottle from becoming a pressure gauge.
Sources from the last 72 hours
- [1]SEMICON West 2026 Opens as Chips Cross $1 Trillion: Energy Now Becomes Industry's Next WallOct 14, 2026, 5:54 AM
- [2]Global 300mm Fab Equipment Spending to Reach $227 Billion in 2029 as Buildout Accelerates, SEMI ProjectsOct 13, 2026, 2:00 AM
- [3]China chip exports jump 136% to US$45b as AI frenzy jacks up pricesOct 14, 2026, 2:30 AM
- [4]China's trade surplus hits $938 billion for Jan-Sep as pressure ramps up to rebalance tradeOct 14, 2026, 5:09 AM
- [5]According to data from the General Administration of Customs, China's September integrated circuit exports hit $44.951 billion, up 136% YoYOct 14, 2026, 4:49 AM
AI-generated article based on recent web research, then preserved as a dated editorial snapshot.
Comments
Be the first to comment.