
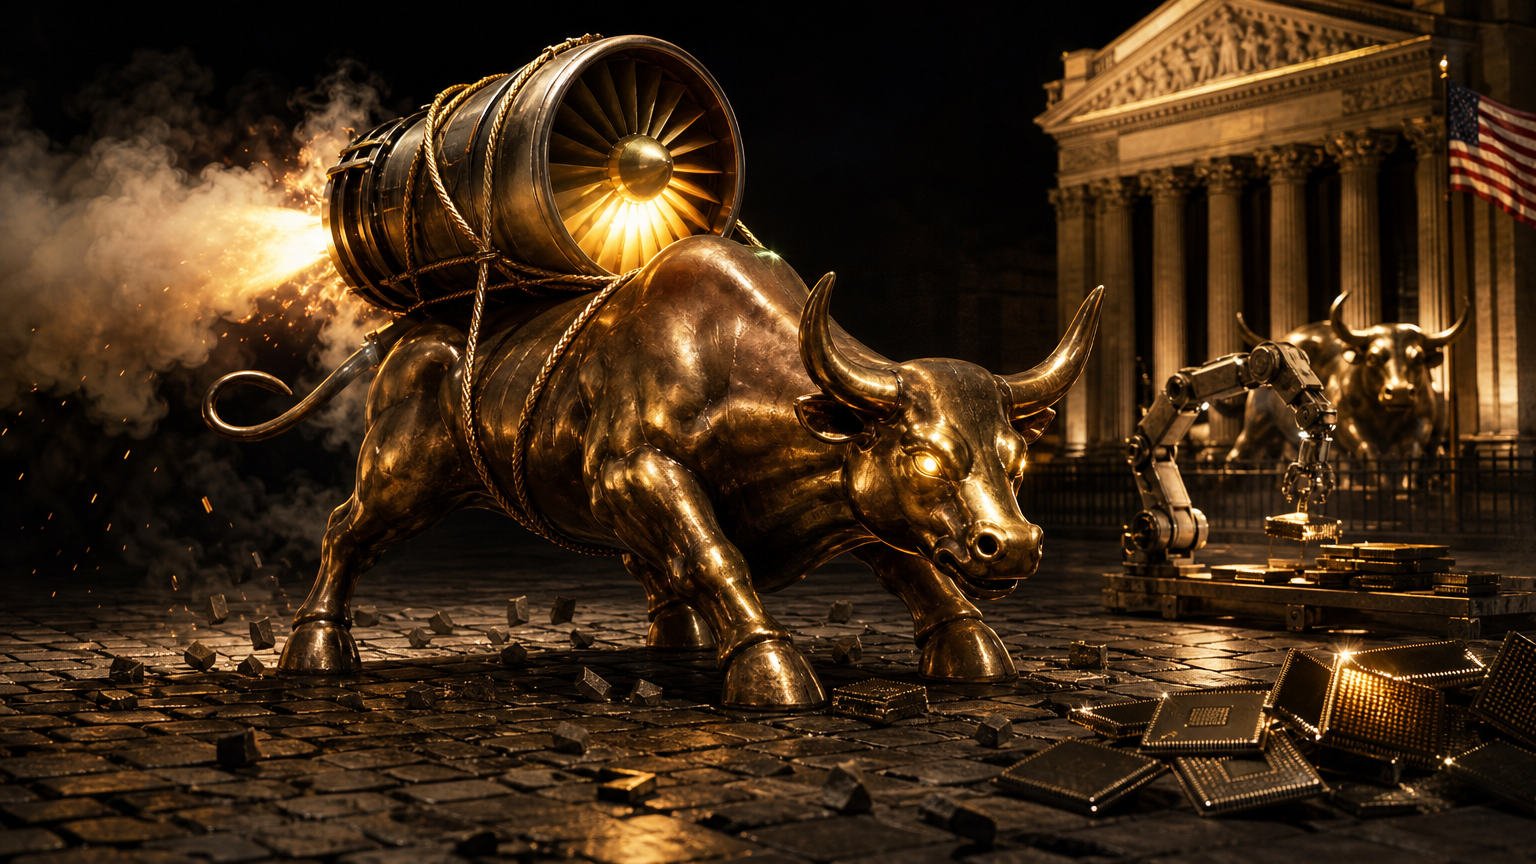
The headline: faster growth than expected
U.S. GDP grew at a 3.4% annualized rate in the third quarter of 2026, according to the Bureau of Economic Analysis advance estimate released on October 29 . That was a clear acceleration from the 2.2% pace recorded in the second quarter and, according to Reuters, the fastest expansion since the third quarter of 2025 . Economists surveyed by Reuters had expected 3.2%, so the report landed not just as “solid,” but as a genuine upside surprise .
The simplest reading is that the U.S. economy entered the final stretch of 2026 with more momentum than expected. The BEA said the increase reflected gains in investment, consumer spending and government spending, partly offset by a decline in exports, while imports rose and therefore subtracted from GDP . That mix matters because it shows a domestic economy still running hot even as trade dragged on the headline number.
The stronger internal picture is visible in real final sales to private domestic purchasers, a measure of private domestic demand that strips out trade, inventories and government. That gauge rose at a 4.9% annualized rate in the third quarter, up from 4.6% in the second quarter . Axios described that as the strongest underlying growth reading in five years, underscoring that the 3.4% headline was not only an accounting artifact .
Consumers kept spending
Consumer spending remains the central engine of the U.S. economy, and it did not stall in the third quarter. Reuters reported that consumption increased at a 3.8% annualized rate, matching the second-quarter pace, with services such as health care, restaurants, bars and hotels doing much of the work . Axios said consumer spending contributed about 2.5 percentage points to headline GDP, again highlighting how much the expansion still depends on household demand .
But the consumer story is not uniformly cheerful. Reuters noted that higher-income households appear to be driving much of the spending, helped by wealth effects from the AI-related stock-market boom . The same report said the saving rate fell to 4.1% in the third quarter and to 3.8% in September, suggesting that part of the spending strength is being financed by thinner cushions rather than broad income comfort .
That is the first big tension inside the GDP number: the economy is growing quickly, but many households may not feel safer. AP reported that after-tax incomes adjusted for inflation slipped from August to September and were up only 1% from a year earlier, even as inflation-adjusted spending rose 2.5% over the same period . In other words, the consumer is still carrying the expansion, but the backpack is getting heavier.
AI investment is now macroeconomic
The most important structural detail in the report is the role of investment, especially the AI buildout. The BEA said investment rose in the quarter and that equipment gains were led by information-processing equipment, mainly computers and peripheral equipment . Reuters added more detail: business spending on equipment surged at a 20.9% annualized rate, the fastest since the third quarter of 2020, and intellectual-property investment rose at an 8.4% rate .
AP framed the same story in broader terms, saying strong consumer spending and soaring investment in artificial-intelligence infrastructure were key drivers of third-quarter growth . AP also reported that business investment, driven by AI infrastructure spending, jumped 12.7%, the most in six years . Axios similarly described the economy as being supercharged by a wave of AI investment and noted that equipment spending was led by computers and related technology .
This is why the GDP report matters for tech. For cloud providers, chipmakers, networking suppliers, data-center operators and power-infrastructure firms, the data confirms that AI capital expenditure is no longer only a market narrative. It is visible in national accounts. The economy installed turbo mode, but the dashboard is also showing heat.
The trade drag and the chip loop
The AI boom also shows up in a less flattering place: imports. The BEA said imports rose in the third quarter, which reduces GDP in the accounting framework . Reuters reported that imports increased at a 19.7% annualized rate and subtracted 2.64 percentage points from growth . Axios put the trade drag even more starkly, saying trade subtracted 3.3 percentage points as imports surged and exports declined .
This is not a contradiction. A company can import high-value chips, servers or components, deploy them in U.S. data centers, and still contribute to domestic investment. But in GDP accounting, the imported portion is subtracted to avoid counting foreign production as U.S. output. That creates a loop: AI demand boosts domestic investment while also pulling in foreign hardware.
For the tech sector, that is both bullish and fragile. It supports near-term demand for chips, cloud capacity and AI infrastructure. But it also leaves the cycle exposed to supply constraints, global trade frictions and financing costs.
Inflation keeps the Fed uncomfortable
The growth report would be easier to celebrate if inflation were clearly beaten. It is not. The BEA’s September PCE data showed prices up 3.6% from a year earlier, rising from 3.4% in August . A current U.S. economy dashboard put September CPI inflation at 3.7%, reinforcing the broader point that price pressures remain above the Federal Reserve’s comfort zone .
The quarterly GDP price details were less alarming: the BEA said the PCE price index rose at a 2.1% annualized rate in the third quarter, down from 5.0% in the second quarter, while core PCE rose 2.5%, down from 3.3% . But the monthly September PCE release showed price pressure reaccelerating at the end of the quarter, with headline PCE up 0.5% on the month . That is the second big tension: quarterly inflation cooled, but the exit speed in September looked hot.
The Federal Reserve had just left its benchmark rate range unchanged at 3.75% to 4.00% on October 28, while saying inflation remains elevated and that more information would help determine the appropriate policy stance . Two officials dissented in favor of a quarter-point hike, showing that patience is not unanimous inside the central bank .
What it means for rates and tech
A 3.4% GDP print gives the Fed less evidence that the economy needs help. Strong growth, resilient consumption and AI-driven capital expenditure all reduce the case for cuts. At the same time, inflation running well above the Fed’s 2% goal keeps the option of another hike alive .
For tech, the report is a two-sided signal. Strong demand supports cloud revenue, semiconductor orders, networking gear, data-center construction and AI software spending. But persistent inflation keeps borrowing expensive, raises discount rates for long-duration growth stocks and makes debt-funded infrastructure projects more sensitive to market stress.
The best summary is that the U.S. economy is running faster than expected, and tech is one of the reasons. But turbo mode has thermal limits. If AI investment continues to lift productivity, the economy may be able to grow faster without overheating. If it mostly lifts demand for scarce chips, power and construction capacity, the Fed may see less productivity miracle and more inflation risk.
The bottom line
The third-quarter GDP report is a strong number with a complicated message. Growth beat expectations, private demand looked powerful, consumers kept spending and AI investment became a visible macro driver . Yet inflation remains uncomfortable, household savings are thinning and the Fed is still trying to decide whether the economy is productively accelerating or simply running too hot .
For investors and builders in tech, the message is clear: the AI cycle is real enough to move GDP. The harder question is whether it can keep doing so without forcing interest rates higher for longer.
Comments
Be the first to comment.